Inventory Audit Services in Delhi
Strengthen inventory accuracy, stock controls and financial visibility with independent inventory audit services in Delhi. We support businesses with physical stock verification, inventory reconciliation, valuation review, movement analysis and identification of control gaps to improve the reliability of inventory records and reporting. Our approach helps businesses gain better visibility into stock accuracy, inventory management, valuation and internal controls while identifying discrepancies and process weaknesses that may affect financial reporting and operational efficiency.
Trusted Across Diverse Business Sectors
Who Typically Needs an Inventory Audit?
An inventory audit is particularly valuable for businesses where stock represents a significant financial investment, operations involve multiple locations, or inventory records are difficult to reconcile. Independent verification can help identify discrepancies, strengthen controls and improve the reliability of inventory information.
Stock-Intensive Businesses
Manufacturers, distributors, retailers and other businesses carrying significant inventory can use independent verification to strengthen confidence in stock records.
- Raw material, WIP and finished goods
- High-value or high-volume inventory
- Frequent receipts, issues or transfers
Businesses With Control or Reporting Needs
Inventory audits can also support management, lenders, investors or assurance teams where independent stock evidence is required.
- Multiple warehouses or branches
- Recurring book-to-physical differences
- Lender, diligence or reporting requirements
Need an independent stock verification or reconciliation review?
Discuss Inventory AuditIndependent review of stock existence, records, movement and controls.
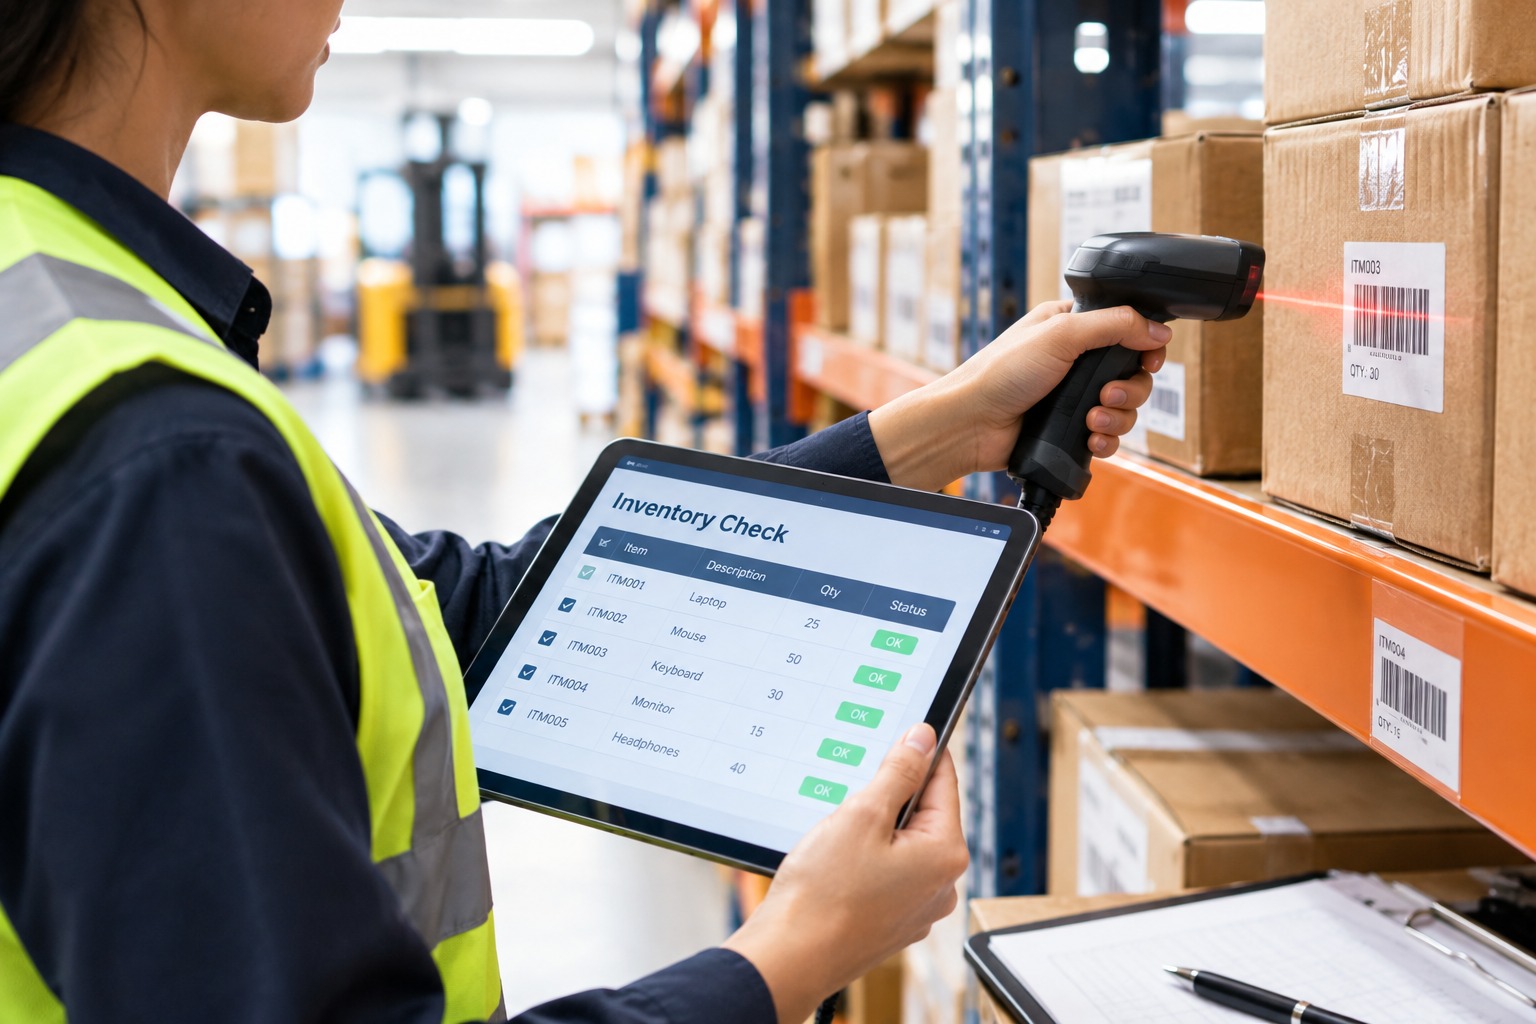
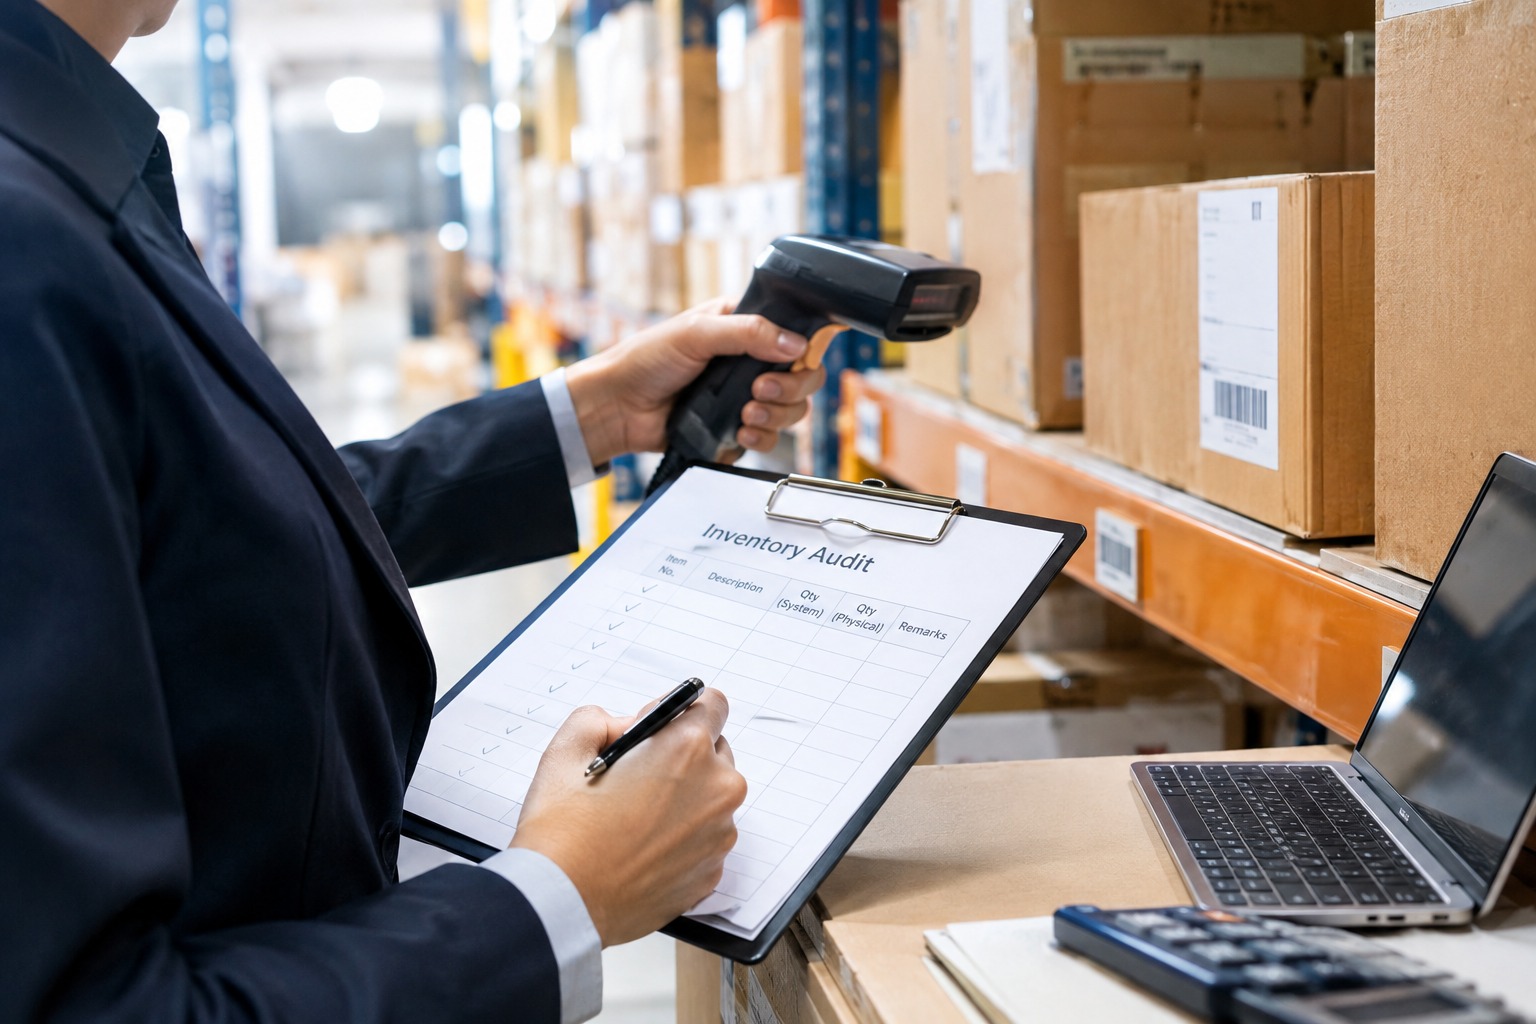
An inventory audit examines whether recorded stock is supported by physical quantities, appropriate documentation and consistent inventory controls. Depending on scope, it can cover raw material, work in progress, finished goods, consumables, spares or other inventory categories.
The engagement may be required by management, lenders, investors, statutory auditors or internal-control programmes. It can also be useful where stock differences, slow-moving items, warehouse issues or recurring reconciliations affect financial reporting or operations.
Inventory audit is most effective when physical verification is connected with stock ledgers, ERP records, cut-off procedures, valuation information and movement documents.
What our inventory audit work can cover.
The scope of an inventory audit is tailored to the entity’s business model, inventory risks, operational complexity and management objectives. Depending on the agreed engagement, our work may cover the following areas:
Physical Stock Verification
Observe or perform agreed physical inventory verification and stock-count procedures, comparing quantities on hand with inventory records and supporting documentation.
Inventory Reconciliation
Analyse differences between physical count sheets, ERP or inventory management systems, warehouse records and financial ledgers to identify discrepancies and potential control gaps.
Inventory Movement & Cut-Off Review
Review selected goods receipts, issues, transfers, sales dispatches and returns around the verification date to assess whether inventory movements have been recorded in the appropriate accounting period.
Inventory Valuation & Ageing
Review available inventory costing, ageing reports and information relating to damaged, slow-moving or obsolete stock within the agreed scope, highlighting items that may require further management assessment.
When businesses typically seek inventory audit support.
Large Warehouse Balances
When inventory represents a significant working-capital or financial-statement balance.
Recurring Stock Differences
Where book stock and physical stock repeatedly fail to reconcile.
Multiple Locations
When management needs a consistent verification approach across plants, branches or warehouses.
Lender / Investor Requirement
When an independent stock review is requested for financing, diligence or monitoring.
Key assertions and control areas in an inventory audit.
Physical Stock
Verify whether inventory recorded in the system can be supported by physical quantities.
Recording
Consider whether stock physically present has been completely captured in the records.
Movement
Review whether receipts, issues and dispatches around the count date are recorded in the correct period.
Cost & Provision
Assess supporting data for cost, ageing and provisions where valuation review is included.
A controlled inventory audit from count planning to reconciliation.
The approach depends on locations, stock categories, materiality and the agreed verification scope.
Plan
Understand locations, stock categories and count procedures.
Freeze
Establish count timing and movement-control arrangements.
Count
Perform or observe physical verification as agreed.
Reconcile
Compare physical results with system and ledger records.
Report
Summarise differences, control issues and action points.
What should your team prepare?
Inventory differences are usually a symptom, not the complete problem.
A stock variance can arise from counting errors, unrecorded movements, incorrect item coding, timing differences, process gaps or weak warehouse discipline. The review should look beyond the final quantity difference where scope allows.
Ageing and slow-moving reports are important because inventory can exist physically but still create commercial or valuation concerns if it is obsolete, damaged or not moving.
For multi-location businesses, a standard count protocol and cut-off process can improve comparability and reduce recurring reconciliation effort.
Need an independent stock count or reconciliation review?
Discuss Inventory AuditWhy businesses work with JJJ & Company LLP for inventory audit.
Inventory verification is not limited to counting stock. Where relevant, our work can connect inventory findings with financial reporting, internal audit, statutory audit and internal-control reviews, providing a broader view of stock-related risks and processes.
Structured Inventory Verification
Plan the verification around stock categories, warehouse locations, inventory systems and movement controls to create a consistent audit approach.
Detailed Inventory Reconciliation
Trace differences between physical quantities and recorded balances back to ERP records, stock registers, count sheets and supporting documents, rather than reporting variances only as aggregate figures.
Inventory Control Perspective
Identify process weaknesses that may contribute to recurring stock discrepancies, recording errors, inventory losses or reconciliation issues, helping management strengthen internal controls.
Financial Reporting Linkage
Consider relevant inventory observations alongside financial reporting, inventory valuation and accounting records, where these areas fall within the agreed engagement scope.
Services closely connected with inventory audit.
Common inventory audit questions.
What does an inventory audit check?
Can inventory audit cover multiple warehouses?
Is inventory audit the same as stock verification?
What happens when physical stock does not match the system?
Can slow-moving and obsolete stock be reviewed?
What information is needed before the count?
Need to discuss your requirement?
Share a few details and our team can review your requirement and discuss the next step.